Business valuation during divorce in Ontario helps establish the value of a spouse’s ownership interest for property division. A valuator may examine the company’s assets or earnings, or compare sales of similar businesses.
The business value alone does not determine an equalization payment. The calculation also depends on each spouse’s other property, debts and permitted deductions. Records of the business value at marriage can affect that calculation.
How Ontario Courts Value Your Business in Divorce
Business valuation in divorce requires expert analysis. Courts do not accept estimates or guesses. You need a professional business valuator or forensic accountant to produce a formal valuation report.
The Three Business Valuation in Divorce Methods
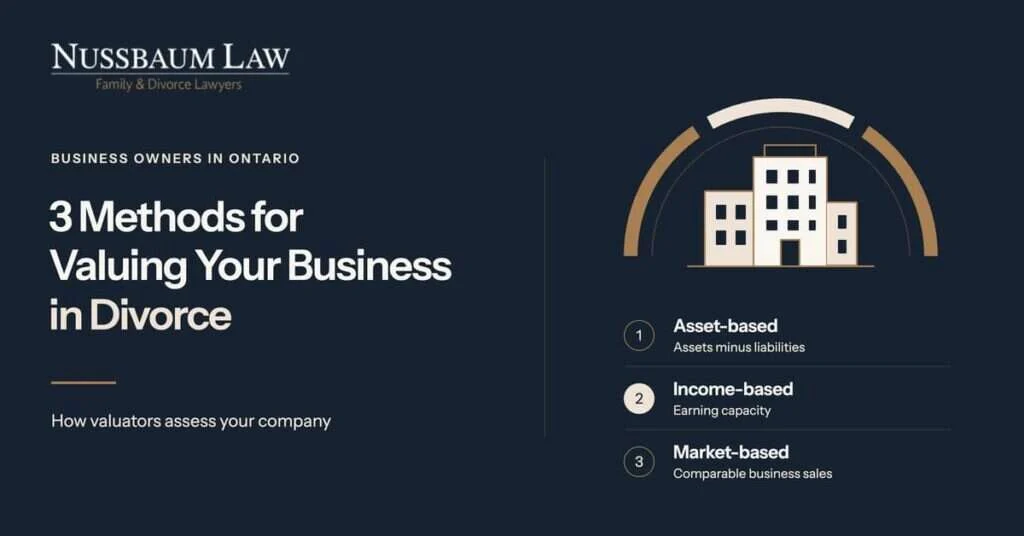
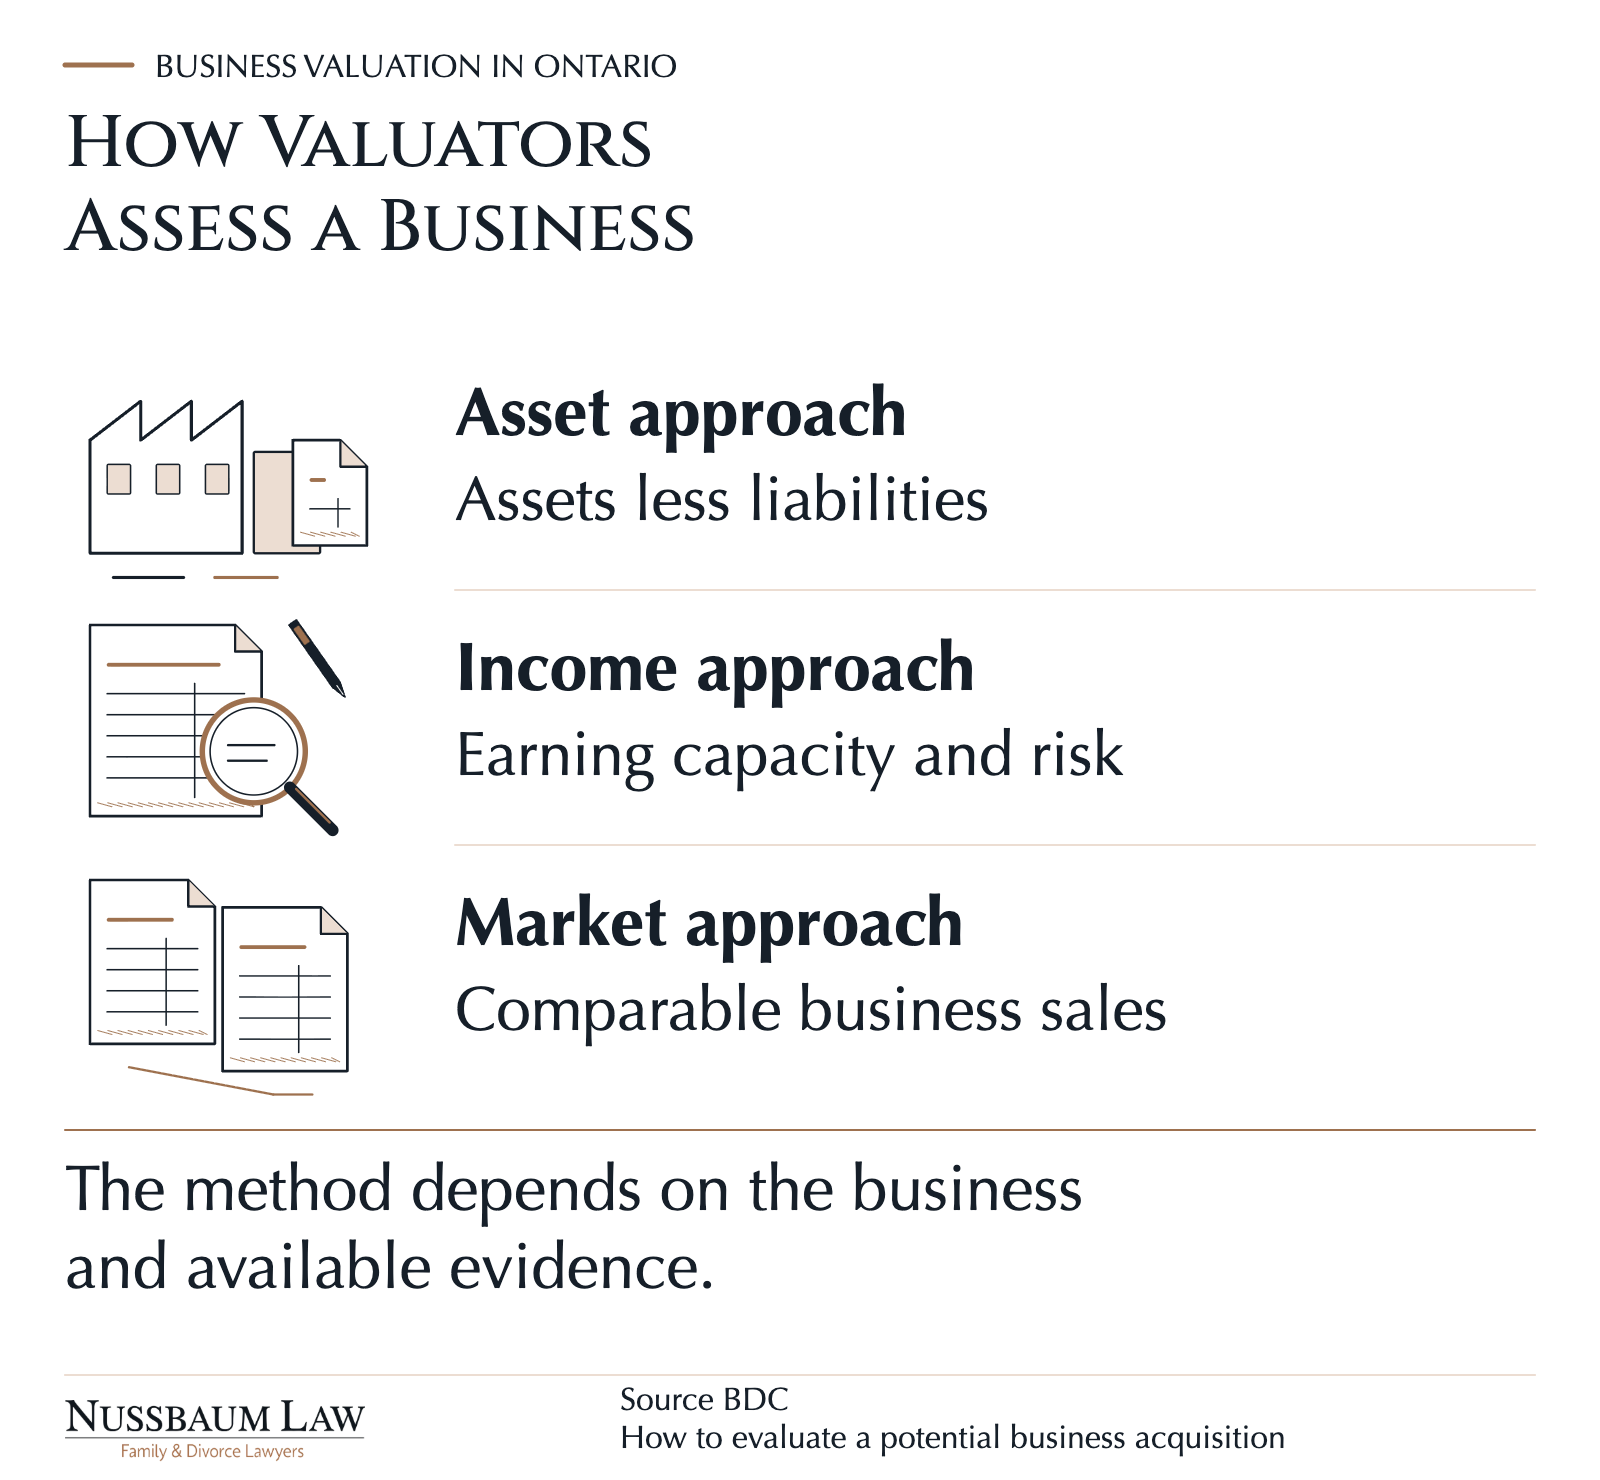
Valuators use three approaches to determine business worth. The method chosen depends on your business type, industry, and financial structure.
Asset-Based Valuation
Calculates net value of business assets minus liabilities. This works well for asset-heavy businesses like manufacturing, construction, or real estate companies. The valuator totals equipment, inventory, real estate, and receivables, then subtracts debts.
However, asset-based valuation undervalues businesses with strong earnings or goodwill. A law practice may have few physical assets but generate substantial income.
Income-Based Valuation
Values your business based on earning capacity. Valuators examine historical performance, project future earnings, and apply industry-standard multipliers.
In a hypothetical illustration, $400,000 in annual EBITDA multiplied by four gives $1.6 million. A valuator must justify the multiple and assess any debt, cash or other adjustments needed to value the ownership interest.
A valuator selects methods suited to the business and available information. A multiple is not a substitute for examining the company’s financial records and risks.
Market-Based Valuation
Compares your business to recent sales of similar companies. Valuators research transactions in your industry, adjust for size and profitability differences, and determine what buyers pay for businesses like yours. This requires sufficient comparable sales data in your industry.
Why the Valuation Date Matters
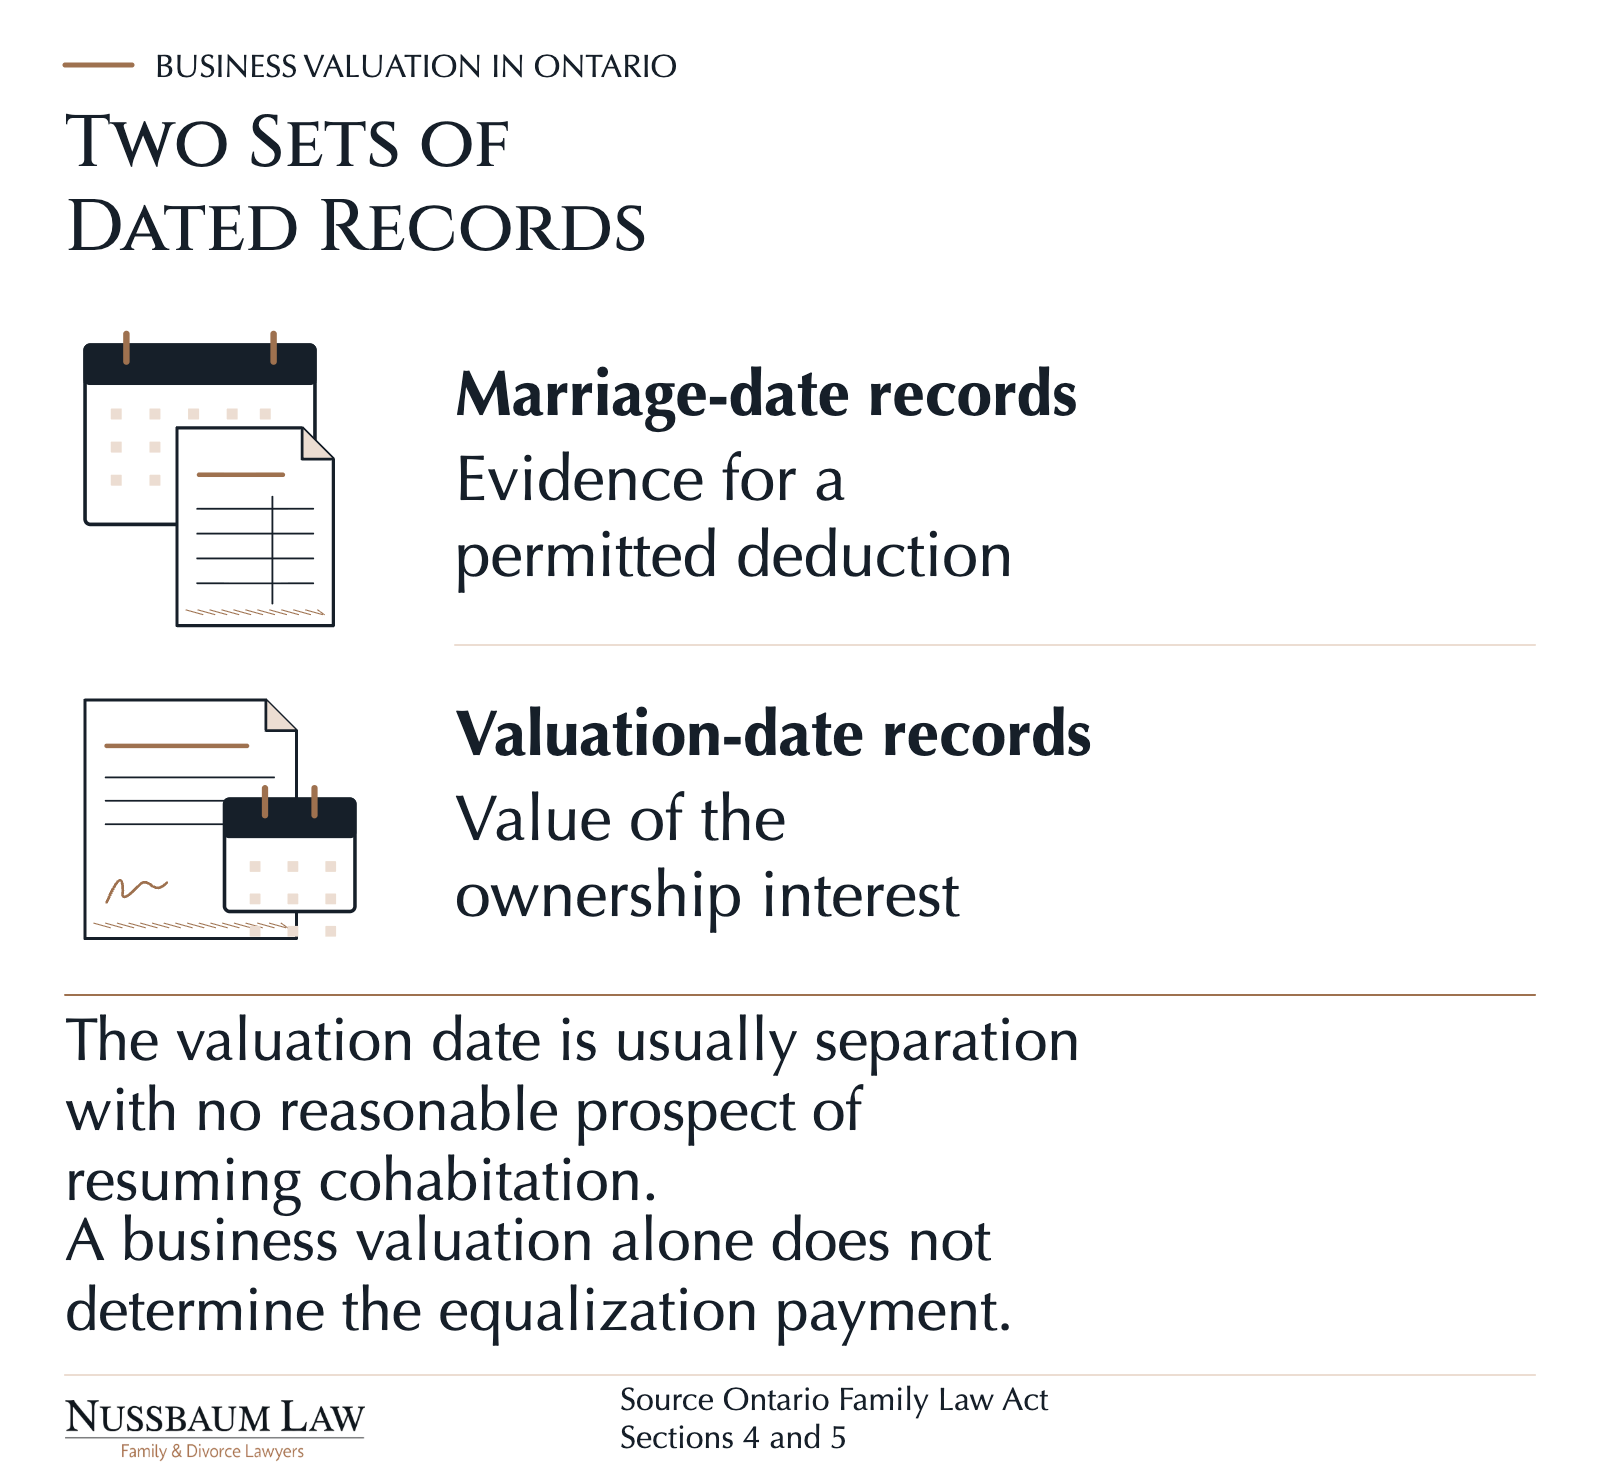
Ontario’s statutory valuation date is the earliest of the events listed in section 4 of the Family Law Act. For a separating couple, this is usually the date they separate with no reasonable prospect of resuming cohabitation.
The valuator needs records for the relevant date. If you owned the business when you married, marriage-date records may also support a permitted deduction.
A later sale price or loss does not automatically replace the valuation-date figure. Ask the valuator to distinguish evidence about the business at that date from changes that happened afterward.
When Your Business Gets Included vs Excluded
Not every dollar of business value counts toward equalization. The timing of when you acquired or built the business determines what gets included in net family property.
Business Started Before Marriage
When you owned and operated your business before marriage, only the increase in value during the marriage gets included in net family property. You can deduct the business value on your marriage date from the separation date value.
A Hypothetical Marriage-Date Deduction
-
- Business value on marriage date. $500,000
-
- Business value on separation date. $1.8 million
-
- Amount included in net family property. $1.3 million
This deduction protects the business value you built before marriage. However, you need documentation proving the marriage date value. Without proof, courts may include the entire separation date value in your net family property.
Business Started During Marriage
When you started or acquired your business during marriage, the entire value on separation gets included in your net family property. There is no marriage date deduction because the business did not exist when you married.
This rule applies even when only your effort and work built the business. Your spouse may have never set foot in your office or contributed directly to operations. Ontario law presumes both spouses contributed equally to marriage assets through their respective roles.
Inherited Business Interests
Section 4(2) of the Family Law Act excludes qualifying property received by gift or inheritance from a third person after marriage. The exclusion can also apply to property into which those funds can be traced, other than a matrimonial home.
Income from inherited property has a separate rule. The donor or testator must expressly state that the income is excluded for that income exclusion to apply.
- Keep the will, gift records and transfer documents.
- Retain share ownership records and statements showing how inherited funds were used.
- Document any sale, reinvestment or change in ownership.
The spouse claiming an exclusion must prove it. Drawing salary or using dividends for family expenses does not, by itself, establish that all inherited shares have lost their exclusion.
The Role of Forensic Accountants in Business Valuation
Forensic accountants provide valuation reports that courts rely on to determine business worth. Chartered Business Valuators must follow CBV Institute’s practice standards when providing valuation services.
Records Behind the Valuation
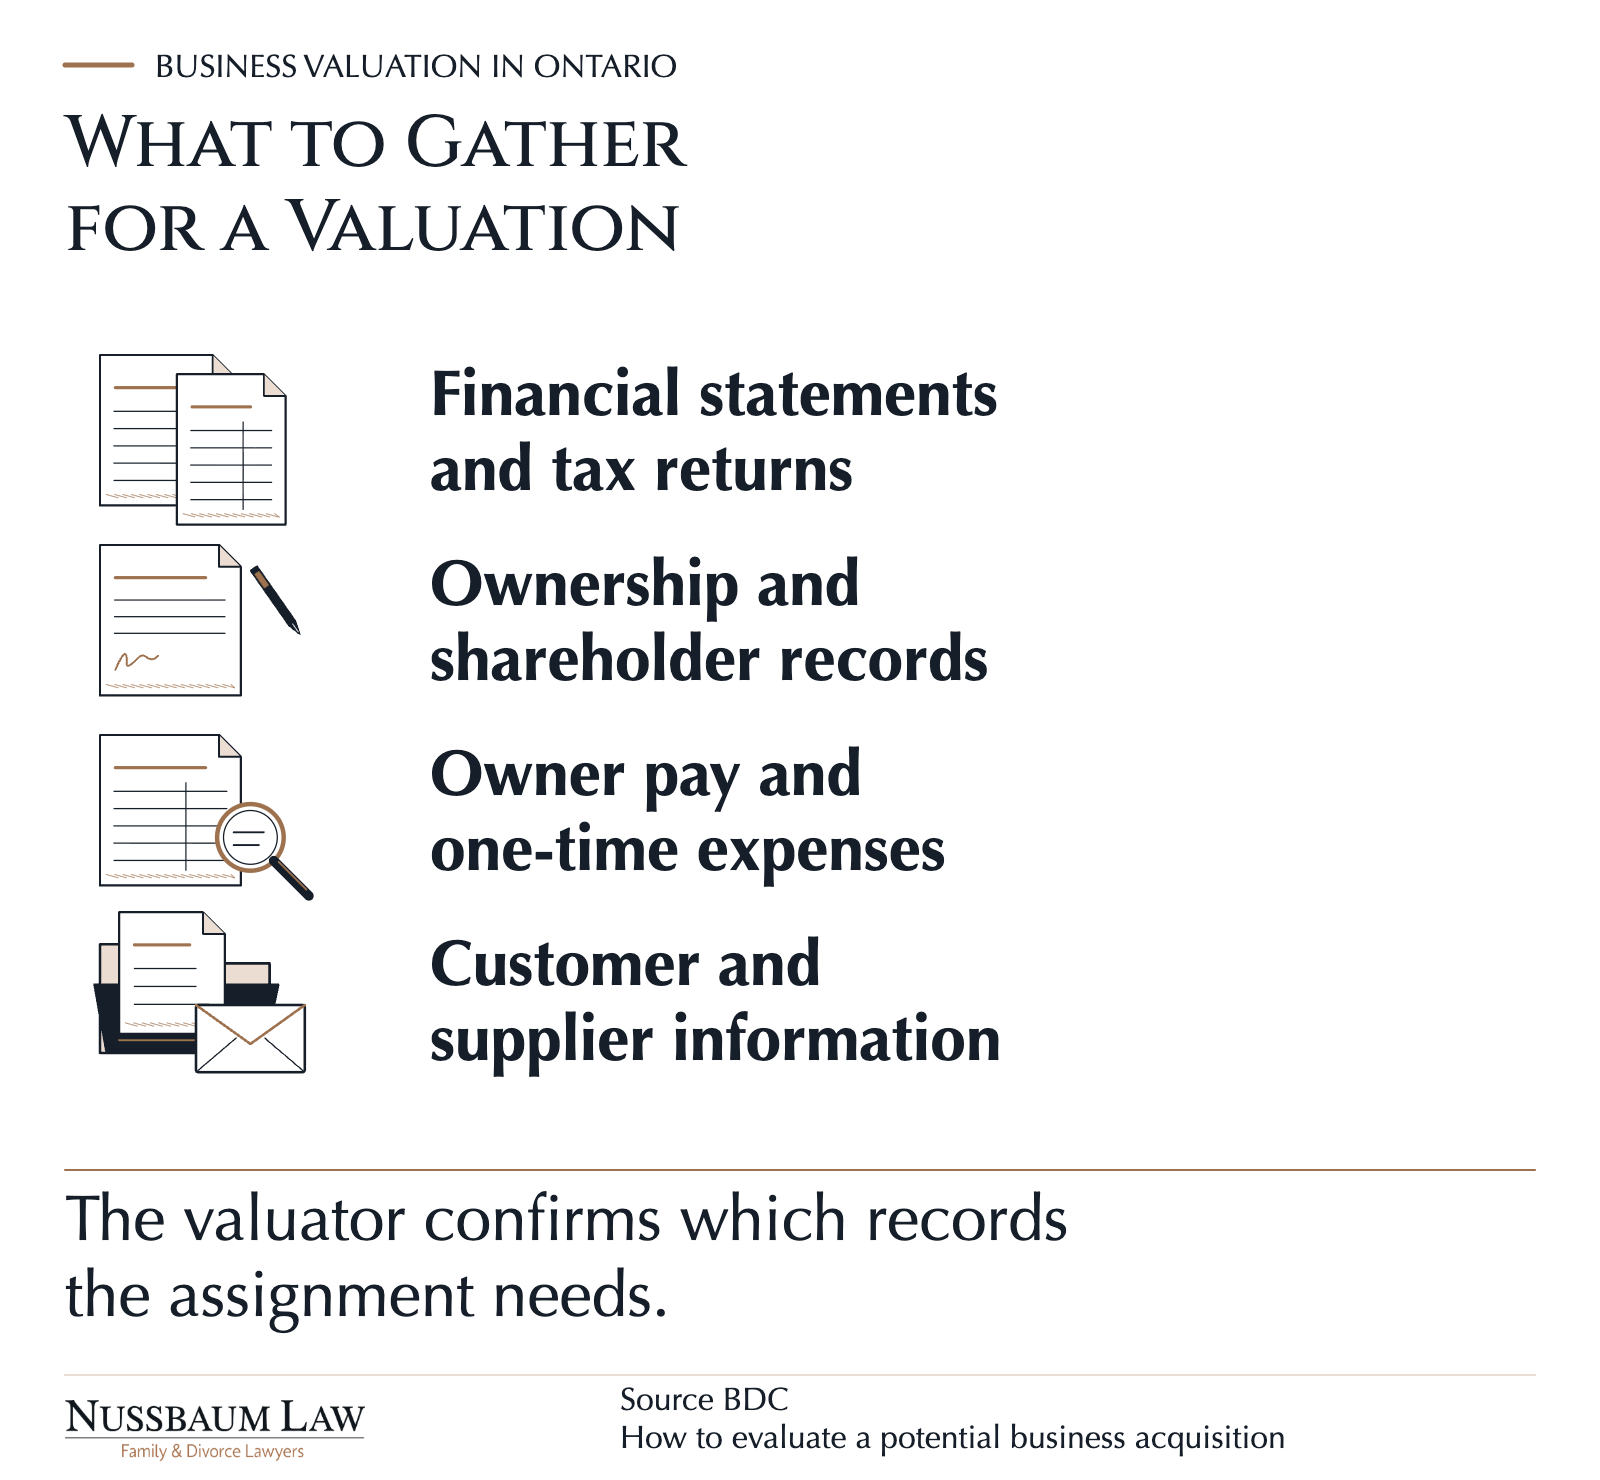
Financial statements from three to five years, tax returns, bank records, shareholder agreements, customer contracts, and industry comparables.
Normalizing Financial Statements
Forensic accountants “normalize” financial statements by adjusting for personal expenses and non-recurring items. This reveals true earning capacity.
Common adjustments include adding back excessive owner compensation, removing personal expenses, adjusting for one-time events, and accounting for family members on payroll who provide minimal work. These adjustments often increase business value.
Dueling Expert Reports
Spouses may retain separate valuation experts or jointly retain one expert. Differences in records, assumptions and methods can produce different valuation opinions.
Under Family Law Rule 20.1, litigation experts must provide fair, objective and non-partisan evidence within their expertise. That duty takes priority over their obligation to the party who retained them.
When reports differ, compare the valuation date, ownership interest, financial adjustments and assumptions. Those differences need examination before either figure is used in settlement discussions.
Active vs Passive Business Income in Divorce
A business ownership interest is property. Salary, dividends and other payments raise separate income questions, including any support calculation.
Keep records showing what the business earned, what it paid you and what it retained. Use separate records to assess income, distributions and retained earnings.
Post-separation growth does not automatically change the statutory valuation date. The ownership records, valuation evidence and any support claim need separate analysis.
Strategies to Protect Your Business in Divorce
Business owners have legal tools to protect their companies. The most effective strategies get implemented before marriage, not when divorce becomes likely.
Shareholder Agreements and Buy-Sell Provisions
A shareholder agreement controls share ownership, transfers, and valuation. Key protective provisions include restrictions on share transfers, predetermined valuation methods, buy-sell triggers, and right of first refusal clauses. These work best when created at business formation.
Marriage Contracts
A marriage contract can address property division and the treatment of a business. Section 52 of the Family Law Act permits spouses to agree about ownership or division of property, subject to the Act’s limits.
A domestic contract must be in writing, signed by the parties and witnessed under section 55. Independent legal advice helps each spouse understand the agreement, but it is not listed as a separate formal requirement in that section.
Under section 56(4), a court may set aside a contract for failures to disclose significant assets or liabilities, lack of understanding, or other contract-law grounds.
Documenting Marriage Date Business Value
When you owned your business before marriage, obtain a professional valuation near your marriage date. This establishes the pre-marriage value you can deduct from net family property. Without it, you face costly reconstruction years later and disputes over historical value.
Maintaining Separate Finances
Clear separation between business and personal finances strengthens your position. Pay yourself a consistent documented salary, avoid running personal expenses through business accounts, keep business credit cards separate, and maintain arm’s length transactions between you and your company.
Warning. Hiding Income Through Your Business
Some business owners attempt to reduce equalization or support by hiding income. These tactics backfire and create serious legal consequences.
Forensic accountants identify income manipulation by looking for sudden income drops after separation, increased personal expenses through the business, deferred compensation, payments to family members, and cash business underreporting.
What Income Concealment Can Cost You
Imputed income based on historical earnings, adverse cost orders requiring you to pay your spouse’s legal fees, credibility damage affecting your entire case, and increased business valuations.
Do I Have to Sell My Business to Pay Equalization?
Selling your business is not required to pay equalization. Courts prefer solutions that allow business owners to keep their companies operational while satisfying equalization obligations.
Alternative Payment Methods
Business owners can satisfy equalization payments through multiple methods.
-
- Other assets. Use savings, investments, or RRSPs to fund the payment instead of business assets
-
- Property transfers. Transfer the matrimonial home or other real estate to your spouse as part of the equalization
-
- Payment over time. Negotiate or obtain court approval for installment payments spread over several years
-
- Business refinancing. Take a loan against business assets to generate cash for the payment
-
- Partner buyout. If you have business partners, they may buy your spouse’s equalization claim
When no other payment method works, courts can order business sale. This typically happens when the business represents your only significant asset and you lack access to other funds or credit.
Payment Timeline Considerations
Courts can order equalization payments over time rather than requiring immediate lump sums. Payment plans up to ten years are possible when circumstances justify extended timelines.
What Supports a Payment Plan?
-
- Your ability to access funds without destroying the business
-
- Whether the business generates sufficient cash flow for installments
-
- The receiving spouse’s financial needs and timeline
-
- Whether security can be registered against business assets
Frequently Asked Questions About Business Valuation in Divorce
Can my spouse become a business partner through divorce?
Your spouse cannot become a business partner or shareholder through divorce unless you voluntarily transfer shares to them or a court orders share transfer as part of equalization. Equalization gives your spouse a right to financial payment reflecting business value, not ownership rights in the company itself.
Most business owners satisfy equalization through cash payment or other asset transfers rather than giving spouses business ownership. Shareholder agreements typically prohibit involuntary share transfers to non-shareholders.
How do courts value professional practices?
Professional practices including medical clinics, dental offices, law firms, and accounting practices get valued using income-based methods. Courts focus on historical earnings, client retention, and transferability.
Personal goodwill versus practice goodwill affects valuation. Personal goodwill reflects your individual reputation.
Practice goodwill reflects the business’s reputation independent of you. Courts typically include practice goodwill but may exclude personal goodwill that cannot transfer.
What happens when business value drops after separation?
A later decline does not automatically replace the business value used on the statutory valuation date. A valuator may need to distinguish later events from information about risks that existed at that date.
The court has a separate power under section 5(6) of the Family Law Act to depart from equal division where equalization would be unconscionable, considering the listed factors. A business loss alone does not establish that test.
Does my spouse get business income after separation?
Separation alone does not automatically make your spouse a shareholder or give them a right to every business distribution. Existing ownership rights, agreements and court orders can change the answer.
Support and property remedies must be considered separately. Under section 11 of the Family Law Act, a court can order a share of business profits or a share transfer to avoid a forced sale or serious impairment of an operating business.
What if I started the business using family money or inheritance?
The source and timing of the funds matter. Section 4(2) allows exclusions for qualifying gifts or inheritances from a third person received after marriage and property into which they can be traced, other than a matrimonial home.
Keep records of the original transfer, the investment in the business and the ownership interest you received. The spouse claiming the exclusion must prove it.
Do not assume the exclusion is always limited to the original contribution or that every later increase is automatically shared. The excluded property and any income require separate analysis under the statutory rules.
Get Business Valuation Guidance
The business valuation is one part of the equalization calculation. Your other property, debts, permitted deductions and exclusions also affect the payment.
At Nussbaum Law, we work with forensic accountants who understand business valuation complexities. We represent business owners throughout Toronto, Vaughan, and Brampton in divorce proceedings where business assets are at stake. We review valuation reports, challenge inflated valuations, negotiate payment terms that allow business continuity, and protect your company from unnecessary liquidation.
Whether you own a professional practice, operate a small business, or hold partnership interests, understanding your business value and exposure before agreeing to settlement terms protects your financial interests. Contact us to discuss your business structure, obtain preliminary valuation guidance, and develop a strategy for your equalization obligations and business operations.