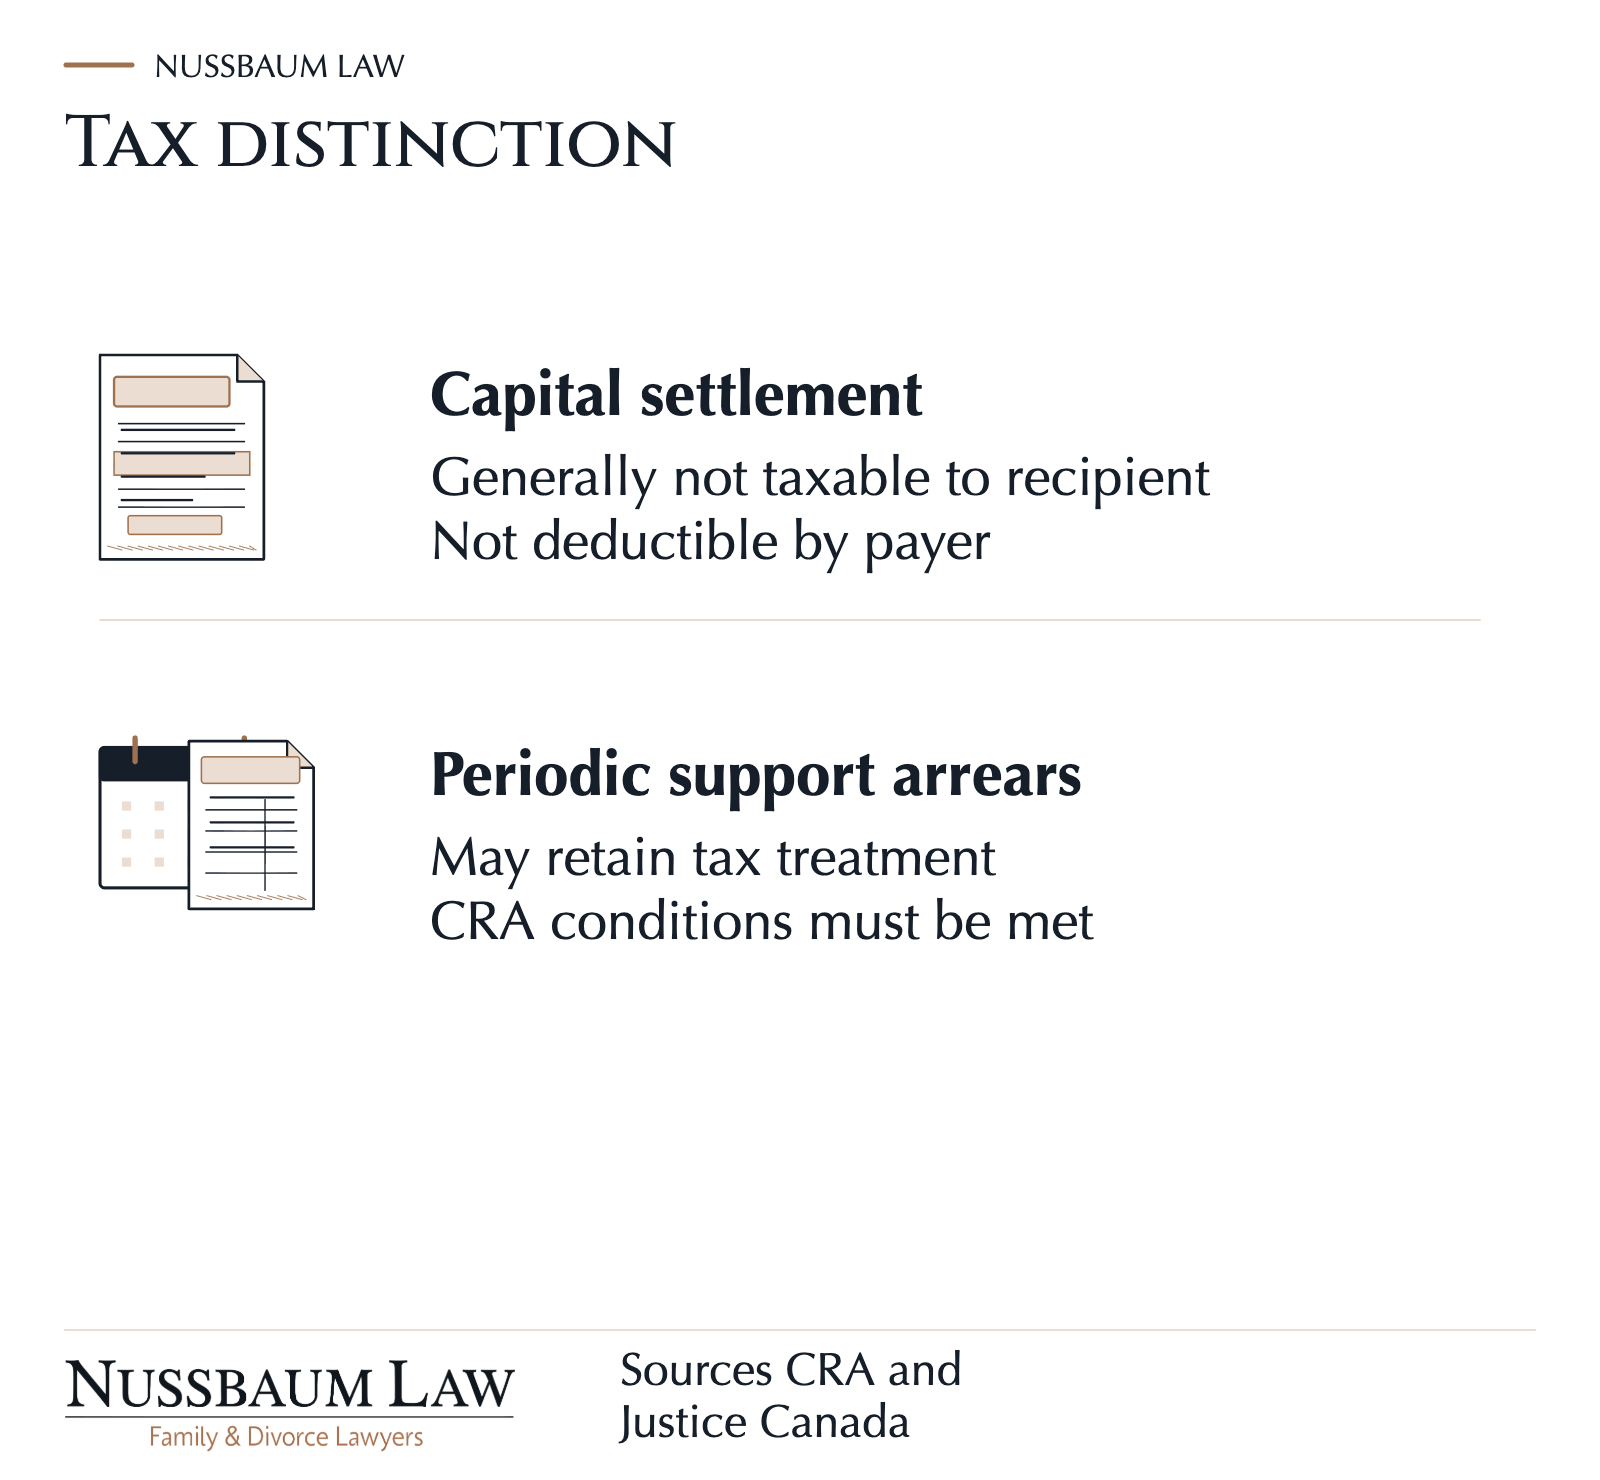
A lump sum can settle spousal support through one payment, but its value depends on the tax treatment and the claims you release. A capital settlement generally isn’t taxable to the recipient or deductible by the payor. A single payment of overdue monthly support can have a different tax result.
Compare the proposed settlement with the after-tax value of monthly support, then examine how each option handles changes in your circumstances. The agreement’s terms determine which support obligations the payment is intended to settle.
What a Lump Sum Can Settle
Spouses can agree to a lump sum, and a judge can order one. Under section 15.2 of the Divorce Act, a court can order a lump sum, periodic payments or a combination. Ontario’s Family Law Act, section 34, also permits periodic and lump sum support.
Establish entitlement to spousal support before choosing a payment structure. The court considers each spouse’s means and needs, their roles during the relationship and the economic effects of separation. An income difference alone doesn’t settle every entitlement question.
A support buyout is separate from property equalization, even when the same settlement addresses each claim. Identify the amount allocated to support and the amount allocated to property. Otherwise, you may disagree later about what the payment settled.
Capital Settlements and Arrears Have Different Tax Rules
A true capital payment that releases support obligations generally falls outside the tax rules for periodic support. The payor doesn’t deduct it as support, and the recipient doesn’t report it as support income. Paying the money in instalments doesn’t automatically turn a capital settlement into deductible monthly support.
For periodic spousal support, deductibility and income inclusion depend on the tax requirements, including the underlying order or written agreement. Check the CRA requirements for a qualifying support amount against the proposed payment. A clause calling a payment deductible cannot override tax law.
One Transfer Can Still Pay Periodic Support
Overdue periodic payments under an existing order or agreement may retain their tax treatment when paid together. Certain court-ordered retroactive payments and advances that secure an existing periodic obligation may also qualify. All applicable conditions must still be met.
A negotiated payment that releases arrears or other support claims can have a different result from simply paying the amounts already owed. Paragraphs 3.44 to 3.46 of the CRA folio’s lump-sum guidance explain the distinction. Have your adviser review the existing obligation and the proposed release together.
How to Compare a Lump Sum With Monthly Support
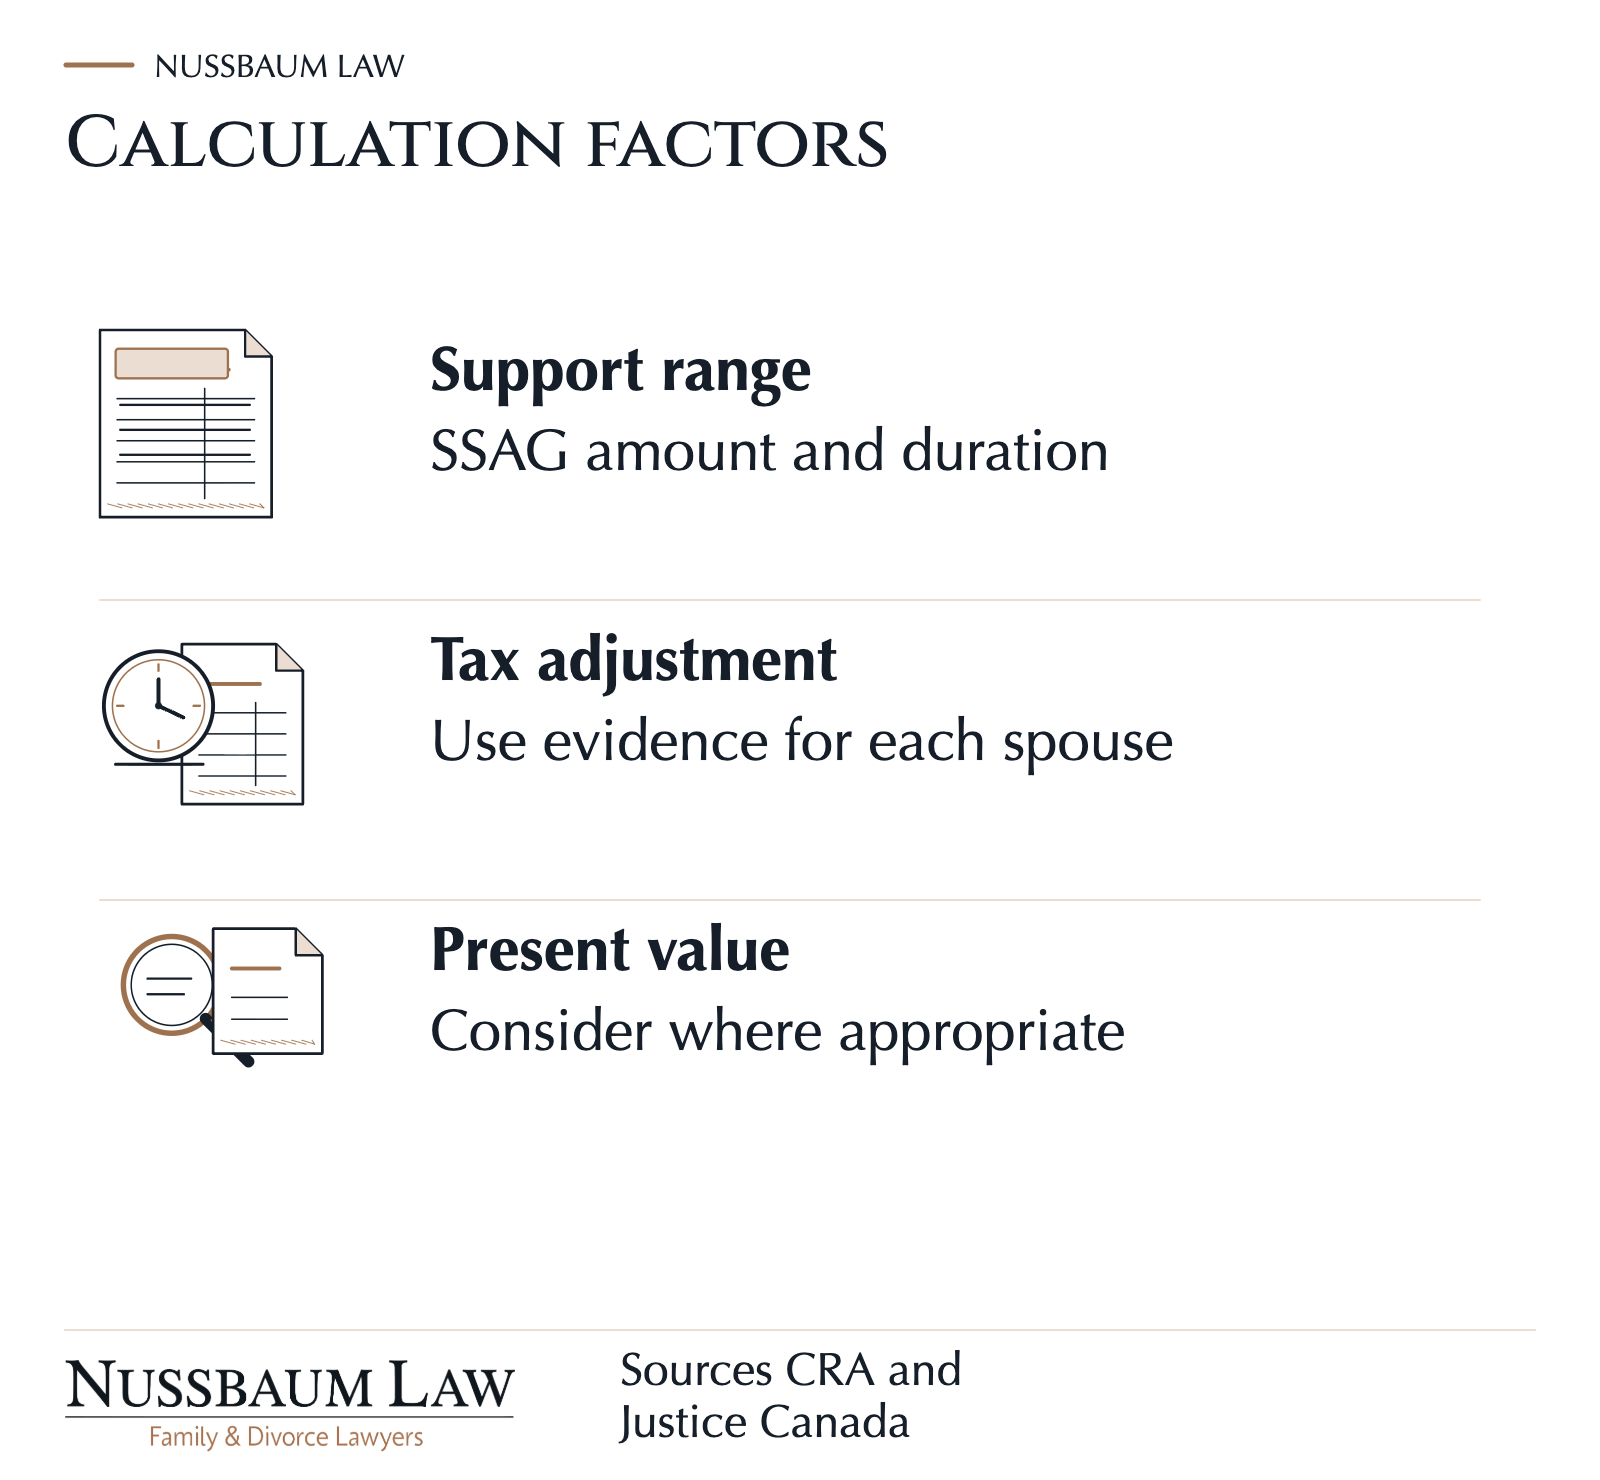
The Spousal Support Advisory Guidelines (SSAG) help estimate the amount and duration of support once entitlement is established. They are advisory rather than legislation, and they don’t produce one compulsory settlement figure. The applicable formula and duration depend on the family’s circumstances, including child support.
Start With the Amount and Duration
Multiplying a monthly amount by the payment period gives an undiscounted total. It doesn’t establish the equivalent capital settlement. An indefinite award has no specified end date, so converting it into a lump sum requires a justified duration or valuation assumption.
Ask to see the income figures, the support range and the proposed duration separately. A lower offer may reflect a shorter payment period, a tax adjustment or a different view of entitlement. Those are separate issues to evaluate.
Compare the After-Tax Amounts
Consider a hypothetical monthly payment of $3,000 that qualifies for the normal spousal support tax treatment. Assume the payor saves tax at 43% on the entire payment and the recipient pays tax at 30%. These illustrative rates aren’t a tax estimate for a particular household.
- The payor saves $1,290 in tax each month, leaving an after-tax cost of $1,710.
- The recipient pays $900 in tax each month and retains $2,100.
Over a year, the assumed tax saving is $15,480, while the payor’s after-tax cost is $20,520. Actual calculations can change when deductions cross tax brackets or affect income-tested benefits. Comparing an untaxed capital payment with the gross monthly total alone misses that difference.
Under the SSAG revised guidance on lump sums, the tax adjustment needs evidence of the spouses’ tax positions. Balancing those positions often involves their midpoint, rather than a universal discount percentage. A midpoint of calculated after-tax values is different from automatically averaging two marginal tax rates.
Assess Present Value and Specific Risks
Receiving money now rather than over time can justify a present-value adjustment. For a short payment period, that adjustment may be inappropriate under the SSAG revised guidance. Ask which payment dates and discount assumptions the calculation uses.
Any additional allowance for events such as illness or an earlier end to employment needs a stated basis. There is no basis for a standard 20% contingency discount in the SSAG revised guidance. Don’t accept an unexplained percentage simply because someone describes it as customary.
When Available Capital Makes a Lump Sum Practical
A lump sum can reduce repeated collection disputes when the payor has accessible funds and a history of missed payments. It may also cover an immediate housing need. Receiving the agreed funds removes the collection risk for that payment; signing a promise to pay doesn’t.
Compare the cost of raising the money with the proposed settlement. Selling investments, borrowing or withdrawing retirement savings can create costs or tax consequences that reduce the available funds. A valuable business or home doesn’t necessarily provide cash for an immediate payment.
A Move Outside Ontario Doesn’t Prevent Enforcement
Ontario has reciprocal enforcement arrangements with every Canadian province and territory. FRO can also work with listed jurisdictions outside Canada, as explained in Ontario’s cross-border support guidance. Check the destination and applicable process before assuming monthly support will become uncollectible.
What You Give Up When You Accept Capital
A recipient needs a spending plan that covers the period the settlement is meant to support. Investment losses, inflation and unexpected expenses can reduce how long the money lasts. An assumed investment return in a settlement calculation is no promise of that return.
For the payor, a later job loss doesn’t automatically create a right to recover money already paid. For the recipient, a later income increase doesn’t automatically create a right to additional support. Assess predictable changes, including retirement, before agreeing to a release.
Finality Has Legal Limits
Treat a paid buyout as difficult to reverse. Still, the statement that courts never have jurisdiction to revisit lump sum support is too broad. The applicable legislation, order and agreement affect the available legal remedy.
Section 17 of the Divorce Act governs variation of support orders and requires a qualifying change for spousal support. A change in circumstances doesn’t, by itself, establish a right to reopen a completed capital settlement. Orders with expired support periods face additional statutory limits.
For domestic contracts, section 56(4) of Ontario’s Family Law Act permits challenges involving undisclosed assets or debts, lack of understanding and other contract grounds. Section 33(4) also permits courts to set aside support provisions or waivers in specified circumstances. Full disclosure and independent legal advice help address these risks before signing.
Monthly Payments and Mixed Arrangements Remain Options
Monthly support may fit when the payor lacks accessible capital or the recipient needs regular income. It can also preserve a route to variation when the legal test is met. The possibility of variation isn’t an automatic adjustment whenever someone’s income changes.
A mixed arrangement combines a capital payment with continuing monthly support. State which obligations the capital amount settles and which monthly obligations remain. Document any review terms and the intended tax treatment of each component.
Keep Child Support Separate
Courts must give child support priority when considering child and spousal support applications together under section 15.3 of the Divorce Act. A spousal support buyout doesn’t cancel a parent’s child support obligations. Address child support before deciding how much capital is available for spousal support.
Review the Records and Terms Before Signing
- Exchange financial records. Review tax returns, notices of assessment and current income evidence. Include business records where relevant, asset and debt information, and the existing support order or agreement.
- Compare the proposals on the same assumptions. Obtain the monthly range and duration, then identify each tax or present-value adjustment in the lump sum proposal.
- Check payment arrangements. Confirm the source of funds, payment date and any security needed before funds arrive. Identify outstanding arrears separately.
- Review the release with independent counsel. Specify the support claims being settled, any obligations that remain and any review terms. Your tax adviser should assess the proposed payment’s tax treatment before you sign.
A family lawyer reviewing your settlement needs the calculation and the draft terms together. An acceptable amount can still accompany unclear payment conditions or a release broader than you intended.
Discuss Your Lump Sum Support Proposal With Nussbaum Law
Contact Nussbaum Law to discuss a proposed support buyout or compare it with monthly payments. Bring your draft agreement, existing support order and financial disclosure. A lawyer can review the proposed release and identify the legal questions to resolve alongside your tax advice.