Hiding income can lead a court to calculate child support using an income amount above the figure a parent disclosed. A judge may impute income when financial disclosure is missing or earnings have been diverted.
The court may also order retroactive support. The amount depends on the evidence and the applicable legal rules. The resulting child support obligation requires accurate income records.
A tax return may leave income questions unanswered
A parent may understate income by omitting cash earnings, diverting revenue or claiming unreasonable business expenses. Personal spending through a corporation can also require closer review of the money available for support.
Under section 18 of the Federal Child Support Guidelines, a judge can examine corporate income when a shareholder’s reported personal income does not fairly reflect available money. Corporate revenue and the parent’s support income are not automatically the same amount.
Relevant records can include employment bonuses, investment income and payments to related people or companies. Bank statements and business records help explain differences between declared income and the money received or spent.
Which income records must you provide?
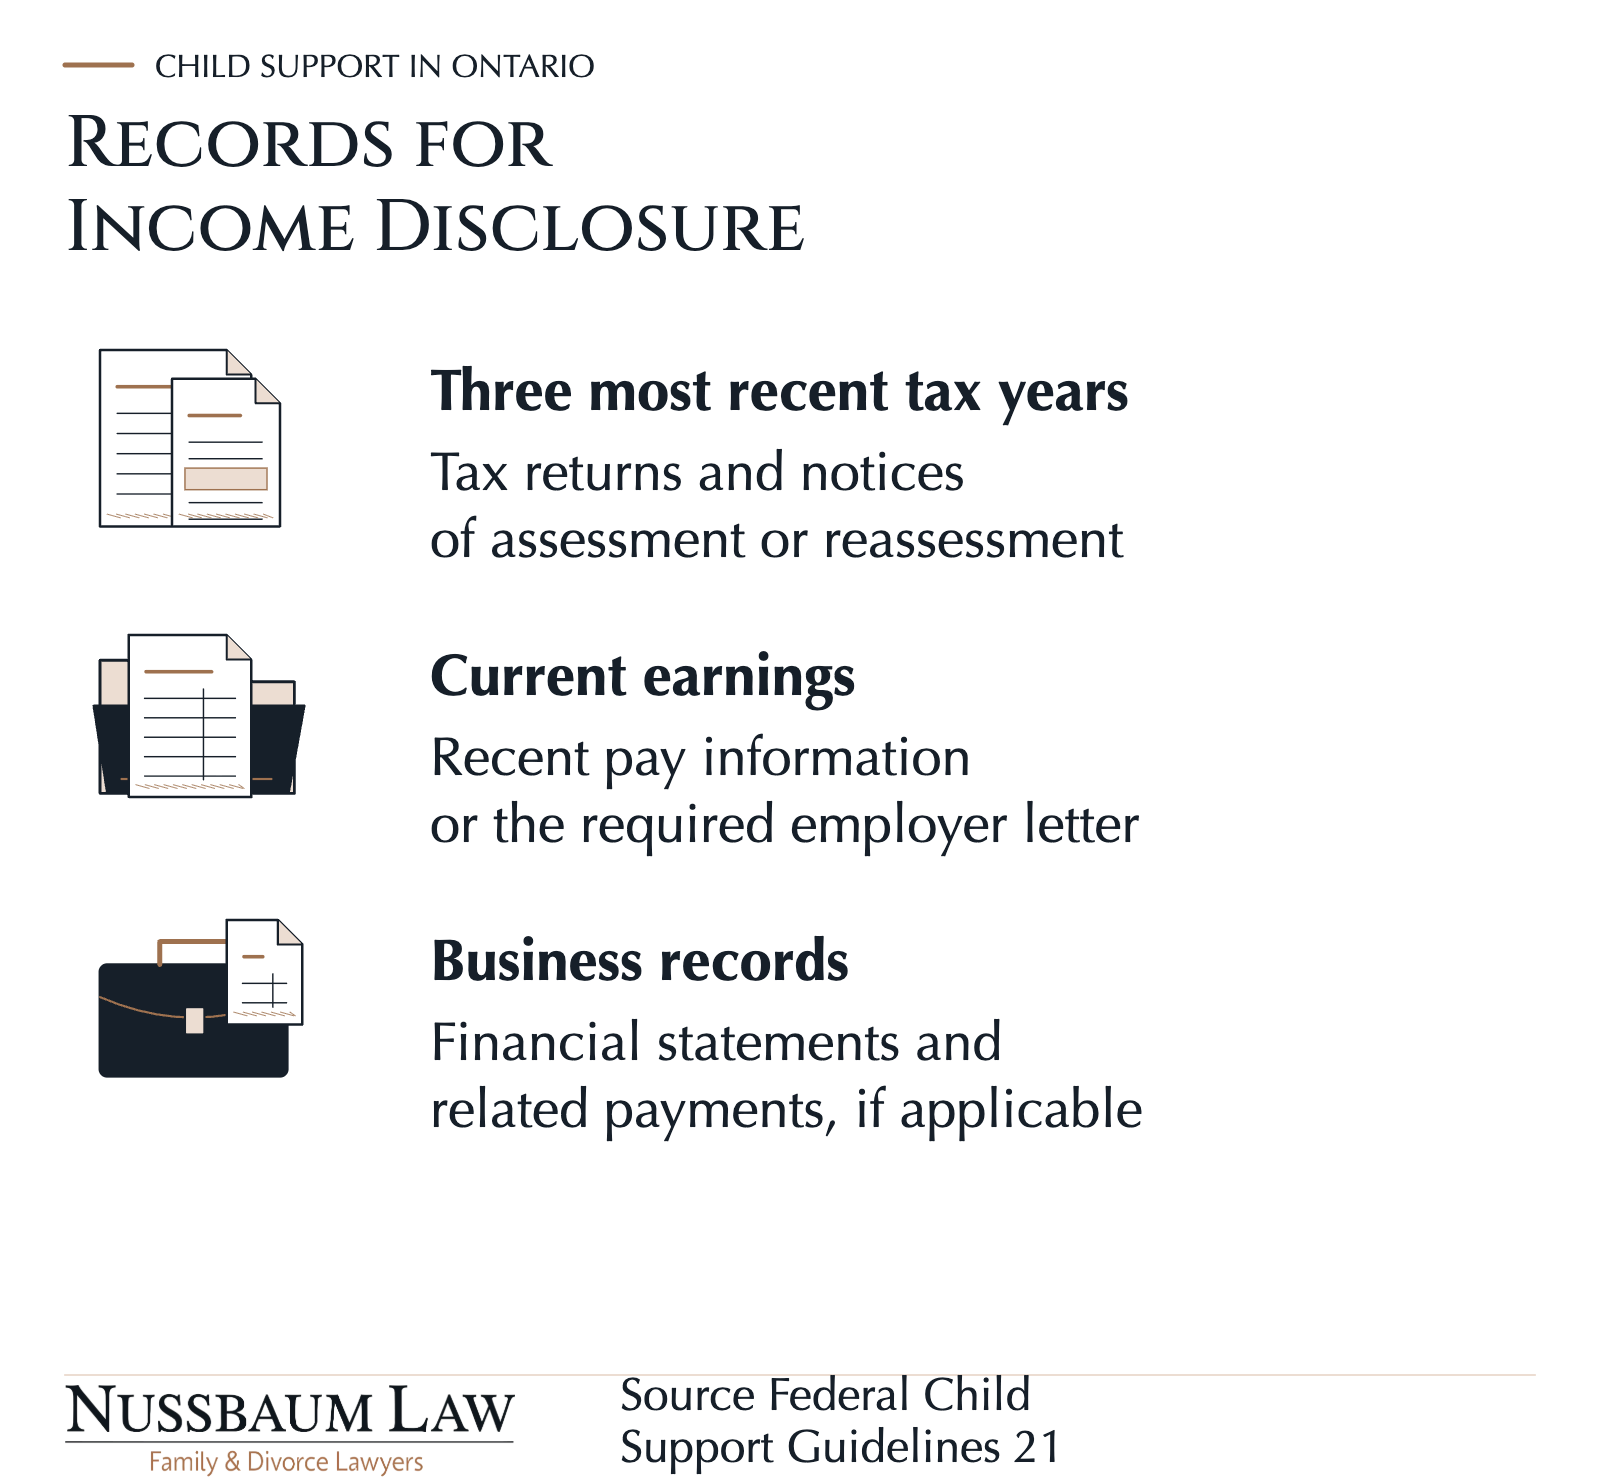
Under section 21, an applicant whose income information is necessary to determine child support must provide specified documents. A respondent whose income information is necessary must also disclose it within the applicable deadline.
- Personal income tax returns for the three most recent taxation years
- Notices of assessment and reassessment for those years
- Current employment earnings information, including year-to-date earnings, or the required employer letter
- Business, partnership, corporate or trust records where applicable
- Current information about other income sources, such as pensions or disability payments
Self-employed parents must provide business financial statements and details of specified payments or benefits to people or corporations with whom they do not deal at arm’s length. A tax deduction does not, by itself, establish that an expense is reasonable for child support purposes.
Ontario’s Family Law Rules also govern financial disclosure. Identify the missing documents and request them through the applicable court process rather than treating an unexplained purchase as proof of concealed income.
Missing disclosure can lead to a court order and costs
If a spouse fails to provide information required by section 21, the other spouse can apply under section 22 for a disclosure order or to proceed toward a hearing. The judge may award costs up to full compensation for those proceedings.
Ignoring a disclosure order creates further risk. Under section 24, the court may strike pleadings, make a contempt order or award costs. It may also proceed to a hearing, draw an adverse inference and impute income.
Imputed income must reflect the circumstances
A judge can attribute an income amount to a parent when the circumstances justify it. Section 19 permits imputation for diverted income, missing disclosure and unreasonable expense deductions, among other grounds.
Imputation determines the income used to calculate support. It is not an arbitrary financial penalty, and a parent’s occupation alone does not establish the right amount.
A lower-paying job needs an explanation
Intentional unemployment or underemployment can justify imputation. Section 19(1)(a) recognizes exceptions for the needs of a child of the marriage or another minor child. It also recognizes the spouse’s reasonable educational or health needs.
For a hypothetical parent who reduces working hours because of a documented medical restriction, the restriction is relevant evidence. The court must assess the circumstances before deciding what income to use.
Retroactive support, interest and costs are separate questions
An understated income can leave a child without support that should have been paid. A retroactive award addresses that shortfall, with the period and amount determined under the applicable legal framework.
In Colucci v. Colucci, the Supreme Court of Canada explained the importance of accurate disclosure and distinguished retroactive increases from requests to reduce existing obligations. A parent cannot assume that a later income drop erases arrears.
Any interest calculation needs the relevant order, dates and applicable rate. Ontario publishes prejudgment and postjudgment interest rates; one percentage cannot support every calculation.
A finding of bad faith changes the costs analysis
Under Family Law Rule 24(10), a court that finds bad faith must decide costs on a full recovery basis and order immediate payment. The court still determines the amount, and an allegation of concealment alone is not a finding of bad faith.
Keep invoices and explain which work resulted from missing disclosure. Legal fees, expert work and other claimed expenses require evidence; they do not automatically become a fixed penalty added to support.
False evidence can raise separate criminal issues
A family court finding about income does not itself produce a criminal conviction. A prosecution requires proof of the specific offence under criminal law.
Criminal Code section 131 addresses knowingly false statements made with intent to mislead under oath, affirmation or other legally specified forms. An inaccurate estimate does not automatically establish perjury.
Section 380 addresses fraud through deceit, falsehood or other fraudulent means. Forged records or unreported taxable income can require separate legal review, but criminal charges and sentences cannot be predicted from a support dispute alone.
Professional reporting does not guarantee licence loss
Under Ontario’s professional-reporting process, FRO sends a notice when a payor has not paid support in three months. The payor has 30 days to respond before FRO may begin reporting them to a professional or occupational organization.
The organization decides its response, which may include an internal review and disciplinary action. FRO does not control that decision, and reporting does not automatically suspend a professional licence.
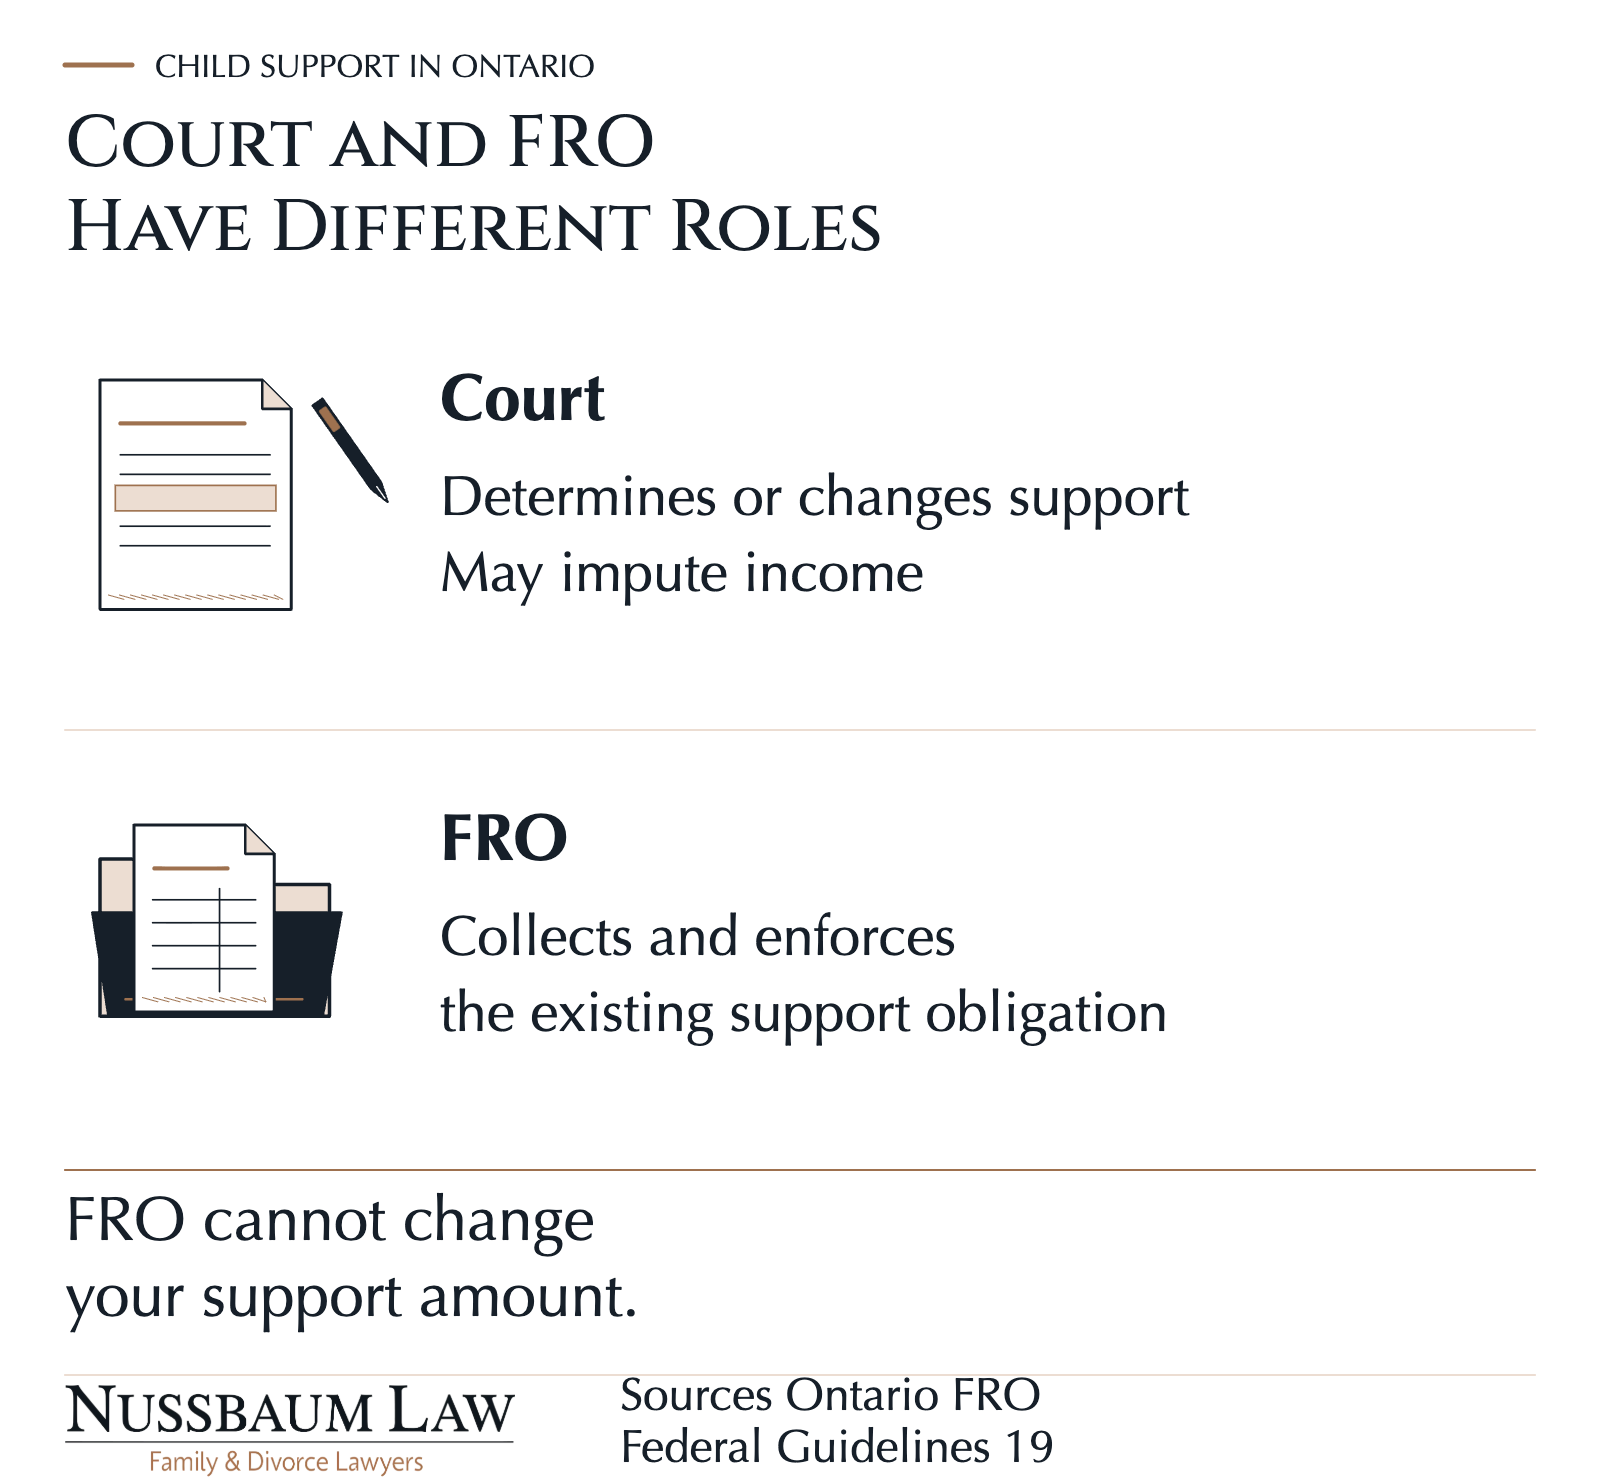
FRO enforces the existing support obligation
The Family Responsibility Office collects, distributes and enforces support under filed orders and domestic contracts. FRO cannot change the amount payable.
- Garnishment of bank accounts and deductions from income
- Deductions from eligible federal payments, including tax refunds
- Credit bureau reporting and property liens
- Driver’s licence suspension and requests for federal licence suspension, including passports
- Writs of seizure and sale, lottery-winnings collection and default hearings
Each enforcement measure has its own rules. For a joint bank account, Ontario states that no more than 50% of the account’s holdings can be taken for arrears, with notice and dispute rights for co-holders.
Read any enforcement notice immediately and respond by its deadline. Contact FRO about payment arrangements rather than assuming that a pending support-change request stops collection.
Foreign income still belongs in the disclosure record
Moving income or assets overseas does not remove an applicable financial disclosure obligation. The court needs the relevant foreign records to assess income available for support.
Ontario’s cross-border enforcement arrangements cover every Canadian province and territory, every U.S. state and specified other countries. The process depends on where the other person lives and which arrangement applies.
The Hague child support convention provides procedures for participating jurisdictions. If the other person lives elsewhere, assess the available legal route before assuming that an Ontario order can be collected through the same process.
Contempt and support default hearings follow different rules
Family Law Rule 31 permits contempt motions to enforce orders other than payment orders. Disobeying a disclosure order can therefore raise a different enforcement issue from failing to pay support.
After a contempt finding, a judge may impose a fine, imprisonment or other authorized terms. The court determines the sanction under Rule 31 and any applicable statutory limits.
For support arrears, a FRO default hearing is a separate process. A judge may order payment arrangements and, in appropriate circumstances, imprisonment for up to 180 days; jail is not an automatic consequence of arrears.
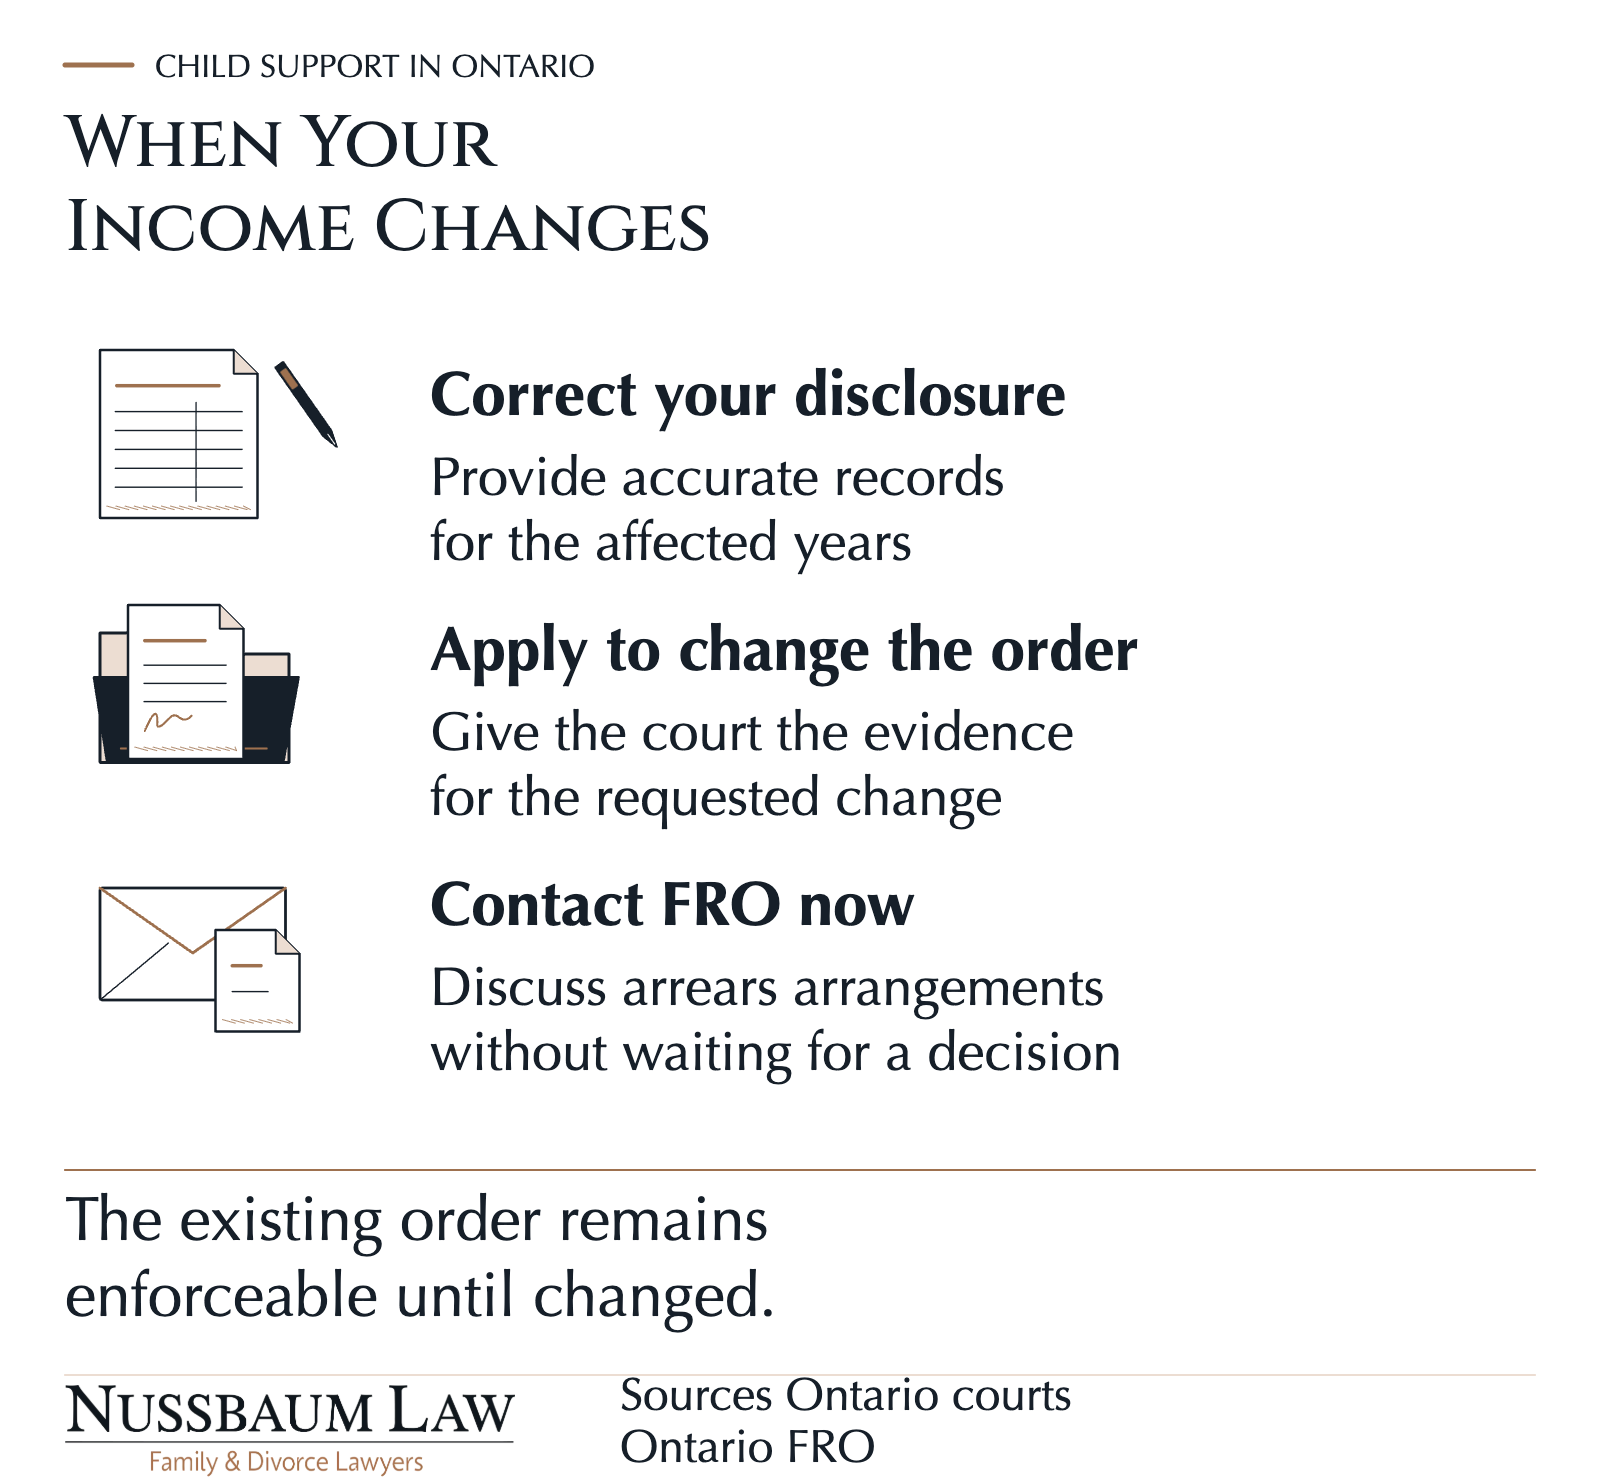
Correct the records and address the support order
Correct inaccurate disclosure with the supporting tax, employment and business records. Identify the affected years so the support calculation can address the period in dispute, including any requested retroactive adjustment.
Use a motion to change when the support order needs revision
If the other party does not agree to a change, Ontario’s motion-to-change process requires court forms, service and supporting financial information. Provide income evidence for every year for which you ask to change or cancel arrears.
Contact FRO separately about arrears payment arrangements. The existing order remains enforceable until changed, and correcting disclosure does not guarantee relief from past costs or other consequences.
Get Advice on Undisclosed Income and Child Support
Contact Nussbaum Law to discuss suspected hidden income, incomplete financial disclosure or a child support amount you believe needs review. Bring your current support order and the financial records you have, along with any FRO notices. A lawyer can review the disputed income and explain the next steps for your circumstances.